In this Moneyweb article, AJ Snyman, Investment Analyst, discusses our disciplined and diligent research process that forms the basis of our strategic approach to investing.
- article
- 3 min read
- 13 May 2024
Never fall in love with a share, even if it has made you wealthy beyond your wildest dreams.
That’s the advice of superstar investors such as Peter Lynch and Warren Buffett.
“One of the important things in stocks is that a stock does not know that you own it. You have all these feelings about it. You remember what you paid. You remember who told you about it – all these little things. And it doesn’t give a damn. It just sits there,” said Warren Buffett.
Another piece of advice from Buffett is to be greedy when others are fearful, and fearful when others are greedy.
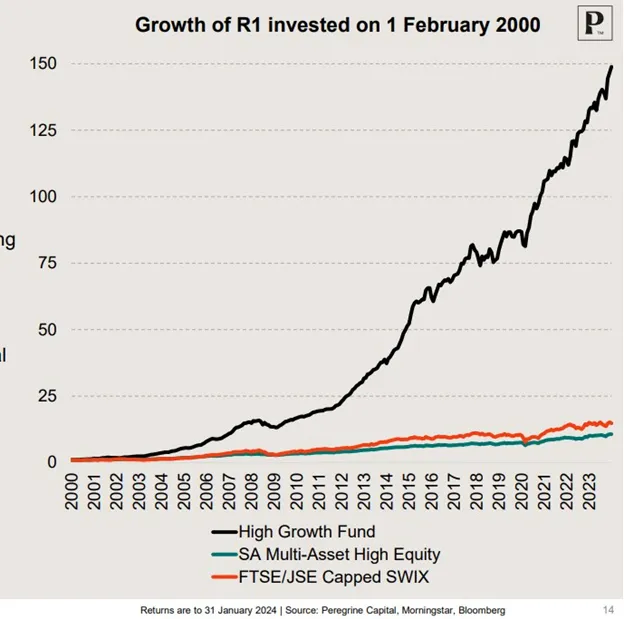
This, says AJ Snyman, investment analyst at Peregrine Capital, is what has guided Peregrine’s investment philosophy for 26 years, steering its Peregrine Capital High Growth H4 QI Hedge Fund (High Growth Fund) to be the first fund in South Africa to achieve 100 times an investor’s initial investment, so a million rand invested in the fund in February 2000 is worth more than R100 million now.*
“It’s very important to be invested alongside your clients because that means your interests are 100% aligned with theirs,” says Snyman. “We have significant skin in the game. This is a broad-based staff-owned company and we, as a block, are the third largest investor in the funds we manage. That gives clients a lot of comfort.”
Peregrine Capital manages a suite of hedge funds, which means it can go long or short an asset. One strategy commonly used by hedge funds is the ‘pair trade’ – for example, going long Shoprite and short Pick n Pay in the retail sector to take advantage of relative differences in performance.
Disciplined research
Peregrine’s impressive 26-year track record has been built on a disciplined and diligent research process that delves beyond analysis of financial statements.
“We need to understand the businesses we invest in better than anyone else,” says Snyman.
“That means knowing the company inside out, meeting with management, suppliers and other stakeholders. All of them have competitors, so we get to know them too. We turn over every rock in search of hidden gems. In the end it comes down to valuation. If you can buy something for less than it is worth, then you have reasonable certainty that you will make money on that investment in time.”
When an analyst’s call goes wrong, other members of the team are called in for a side-check.“You have to accept when you are wrong,” adds Snyman.
This is a crucial safety valve often overlooked in investing. As Jeff Bronchick, founder and portfolio manager at Cove Street Capital, puts it: “We don’t have many rules, but when a stock is down materially relative to its peer group we assign another analyst to formally review it and then force ourselves to buy more or get out. Not surprisingly, the analyst who originally recommended the stock is the last person to want to sell it.”
The chart below shows the performance of the Peregrine High Growth Fund since 2000 relative to SA Multi-Asset High Equity index and the FTSE/JSE Capped SWIX. This demonstrates the benefits of compounding superior returns over time, without assuming too much risk. In fact, the fund’s constituents are selected for their moderate risk, which are similar to those of SA high-equity balanced funds, says Snyman.
Peregrine enforces an internal ‘stop-loss policy’ that compels it to re-examine its investment thesis whenever there’s a drawdown of 10%, regardless of the reason.
This policy has proved its worth over time. After a significant drop in the price of the Fortress B shares in 2018, the team decided to invest in this share at about R8 a share.
The complex dual class share structure of Fortress was shunned by the market and the share price fell significantly when the board altered its dividend policy that year. Peregrine sold its shares at a loss, but avoided a further 50% reduction in the share price as market participants increasingly deemed the share to have no value. Peregrine reinvested into Fortress A and B shares in 2021 and actively collaborated with other shareholders, and the company, to engineer a win-win transaction that established a single share class for the company, unlocking significant value for holders of both share classes.
Trying to eliminate emotions when investing is essential to any successful strategy. Making money in the market is not as easy as buying low and selling high. While you can never entirely remove emotions, you can have guardrails to help navigate this and ensure you stay laser focused on generating superior returns for clients.
“When things get heated and emotional, we always default to a basis question: will this make superior returns?” adds Snyman. “We have no sacred cows. We are a meritocracy. This is a contact sport in investment terms. We challenge each other’s opinions, and never get complacent.”
Volatility is an opportunity
Volatility, rather than being a foe, is an opportunity for nimble investors. Snyman points to Capitec, which was heavily sold after Viceroy Research came out with a 2018 report suggesting the bank had understated its bad debts. The selloff was short-lived (Viceroy’s research was found to be false, misleading and deceptive by the Financial Sector Conduct Authority) and six months later the share price had recovered to its pre-selloff peak. The Covid selloff in Capitec was another opportunity for quick-footed investors to get the shares at a good price.
“We’ve been through difficult cycles before, and we don’t need great markets to generate returns,” adds Snyman.
When financial markets are down, there is usually good reason for that.
“Earlier this year, many fund managers were quoted saying that China is uninvestible because of its weaker economy and consumer sentiment and regulatory risks. Chinese markets were heavily oversold, and we took a different view and aggressively bought Chinese shares, particularly stocks like Tencent which was on a single digit PE [price-earnings ratio] at the time. It has had a decent rally since then. Not surprisingly, many investors are getting interested in China again. Our advantage is that our flat structure allows us to act quickly when we see opportunity,” says Snyman.
Unloved shares
Unloved shares often hide some gems. In 2020, before Covid, Peregrine decided to reduce its exposure to SA. The Covid selloff generated some spectacular profits on put options taken out on the S&P 500. These profits were used to load up on companies that had been smashed by Covid, like Meta, Starbucks, L’Oréal and Estée Lauder.
“We lost sight of how cheap SA had become,” says Snyman. “For example, people were saying that shares like Tsogo Sun were doomed after they went down to R1.80. Less than three years later it was back up at R11. The lesson here was not to become too attached to your most loved shares when opportunities are popping up elsewhere.
“At the moment we are slightly more invested in SA than offshore because there are great opportunities in the mid-cap space,” he adds.
“There are some companies that have found ways of working around problems at Eskom and Transnet, that are not massively geared and are generating good cash flows.
“If South Africa stops scoring own goals like we see at Transnet and Eskom, we are likely to see valuations take off. Foreigners are nowhere to be seen in SA right now, and we need them back in the SA market for a sustained rerating to occur.”
Funds Performance
Risk is What You Don’t See
In this MoneyMarketing article, Grant Dixon, Investment Specialist, discusses how the biggest risks in investing are often the ones investors don’t see and how understanding hidden risks and staying disciplined helps build portfolios that withstand market uncertainty.
- article
- 5 min read
- 4 March 2026
Funds Performance
Investing Money in the New World Order
Profound geopolitical shifts and rapid technological change have left the world in flux. Peregrine Capital is capitalising on the opportunities this brings as it navigates investing in this volatile new landscape.
- article
- 5 min read
- 17 February 2026
Stay connected
Subscribe to Peregrine Capital's regular communications. Gain access to up-to-date news and insights from our world of Hedge Funds, delivered straight to your inbox.
Stay informed. Stay Educated.